The economics behind low interest ratesBY ANDREW WILSON | VOLUME 16, ISSUE 2 People often ask why interest rates are so low, what is a negative interest rate and when will rates rise again. This paper explains the economics behind low interest rates, considers ... Get articles like this delivered to your email - Sign up for the free weekly newsletter  More Articles |


Latest News
Insignia chief draws 'hard line' on NCAs giving retirement advice
Insignia Financial chief executive Scott Hartley said he draws a hard line when it come to the new class of advisers (NCAs) giving retirement advice.
Entireti launches consulting program for AFSLs
Entireti has launched a new program to support self-licensed firms to design and execute strategic initiatives, while improving performance and competitiveness.
Private credit bodies issue investor protection guidelines
Australia's private credit industry has introduced new voluntary guidance aimed at strengthening lending practices, improving transparency and addressing regulatory concerns around investor protections.
Many advised Aussies feel financially worse off: Report
A new report reflects that despite being advised, almost four in 10 Australians (37%) found themselves in a worse financial position than a year before.

Further Reading
Cover Story
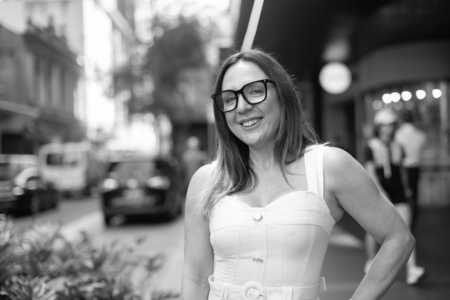
Advice with soul
SACHA BURCHGART
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
Though she initially tried, Sacha Burchgart couldn't escape the call of a career in financial advice; it just took staring down her own mortality to see what's possible when you do things differently. Jamie Williamson writes.
Expert Feed
What people really want when they say 'financial freedom'
APT Wealth Partners highlights the importance of distinguishing the unique financial freedom desires of each client.
Private markets in Australian wealth management: Impressively diverse and a positive outlook
Australian wealth managers' appetite for private markets is growing as increased product varieties and better access continue to drive adoption.
Are weight-loss jabs creating a new advice opportunity?
Clients who lose weight and improve their health often overlook how the change impacts their retirement dynamics and insurance policies.
How technology is turning tax complexity into client clarity
What used to be a relatively simple back-of-the-envelope calculation is now much more challenging, Morningstar says.


Interesting article in that it discusses what should "theoretically" happen. The reality is very different. The RBA has ben reducing interest rates consistently for some time now expecting things to change. It hasn't. Based on this continuing experiment one has to wonder whether the RBA board is in fact showing signs of insanity.
Regardless of how low rates go, consumers are focussing on reducing debt and nothing seems able to change that. One reason is because regardless of what the official rate is, the lenders have not kept pace with the falling rates. In addition to this, wages have stagnated but living costs continue to rise. Name a single utility, food, state or local government charge that has gone down during this period that affects all consumers equally? As a result of increasing living costs in a stagnant wage environment with low interest rates, the best earning potential for consumers is in their offset account.
Australia has a cost problem, it stifles the economy, makes our producers uncompetitive relative to trade rivals and will not be resolved until those at the top of the tree on both the government and corporate sides recognise this.
We, as a nation, cannot afford to continue to fund an ever increasing public service wage bill where PS wages are guaranteed to increase each year when private sector wages don't. That's just one aspect but shows how the unproductive part of the economy is insulated from the issues being faced by the rest. The policy makers don't see the problem because they're not facing them.
Our economy is screwed up and I feel it is because we have in fact lost sight of the fundamentals that make it work. Consumers won't sped unless they know they will have surplus income after meeting their essential living costs. Right now that isn't happening unless you're a public servant who doesn't actually contribute to national GDP in any meaningful way.
What does economic theory have to say about that?