Is insurance broken?BY CHRISTOPHER PAGE | FRIDAY, 27 MAR 2015 6:28PM Is insurance broken? By now you will probably have an opinion about the Trowbridge Report released last week and it is also very likely that you have asked yourself the question ... Upgrade your subscription to access this article
Join the growing community of financial advisers
with unlimited access to our latest news, research and analysis of the industry.
Become a premium subscriber today. |


Latest News
HNW clients value quality over fees: Praemium
High-net-worth (HNW) Australians who receive ongoing financial advice are more confident in their investments than those managing their wealth alone, new research from Praemium and CoreData found.
TAL launches new campaign focused on mental health
TAL has launched a new campaign, working with youth media group The Daily Aus, and partners with the AFLW, aimed at promoting mental wellbeing.
Selfwealth expands into full-fledged wealth platform
Trading platform Selfwealth has launched three managed portfolios, expanding from online brokerage into a wealth platform.
Adviser increase the 'strongest' since FY20: Padua WealthData
The number of financial advisers has risen to 15,169, with net gains of six new members this week, according to Padua WealthData's analysis.

Further Reading
Cover Story
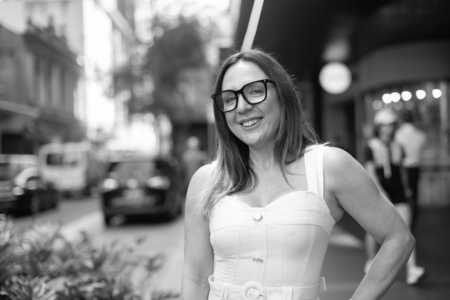
Advice with soul
SACHA BURCHGART
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
Though she initially tried, Sacha Burchgart couldn't escape the call of a career in financial advice; it just took staring down her own mortality to see what's possible when you do things differently. Jamie Williamson writes.
Expert Feed
What America's $1 trillion direct indexing boom tells us about the evolution of MAs
What Australia can learn from direct indexing, a tax-efficient form of managed accounts utilised in the US.
SMSF changes unlikely to deter those seeking greater control over superannuation
HLB Mann Judd's Mitchell Markwick believes the recent changes will not slow down the rapid growth in SMSFs.

Stonepoint is another lesson in fund governance and investor protection
The demise of the Stonepoint Capital Fund may have gone under the radar for many, but proves an important point for independent governance when examined.
A never ending story of levies
The extensive processing period for Shield and First Guardian complaints means financial advisers will likely not be able to see an end to a series of ...


Here's an idea:
Maximum of 80% upfront (i.e. hybrid model 80/20). With an upfront payment allowed only once every five or more years per client.
This would stop the majority of churn, while still keeping risk advisors in business.
Thoughts?
An idea I believe is worth considering:
Stepped Premiums-
As Life insurance products are more likely to move from one insurer to another from a price perspective when the premium is written 'Stepped', I would suggest the industry significantly reduce upfront commissions on Stepped premium contracts. This action may potentially discourage advisers from writing Stepped contracts in most cases where it may be a better long term solution for the client to have a 'Level' premium structure. Maybe also worth considering no new commission payable if a Stepped contract is rewritten within 5-6 yrs (ie. break even point for the insurer).
Level Premiums-
On the other hand, the fundamental reason for writing a 'Level' contact with an insurer is to ensure that the client has a long term insurance solution in place, with that particular insurer. I have not seen stats but I am sure Level premium contacts do not get rewritten with new insurers at the same rate that 'Stepped' contracts. This is because that chances are, the client cannot get the same 'Level' premium pricing with the new insurer as they would be locking in at an older age than the previous contract. As a result of this, the industry could 'encourage' advisers to write more level premium contracts if the commission rates payable on these contracts were more favourable than 'Stepped' contracts.
This may result in less movement of policies from one insurer to another and a more profitable industry which could then return that by reducing insurance premiums.
Hybrid will be good for both advisers and the industry I switched to hybrid 10 years ago and have never looked back. Sometimes I don't break even on hyrid for 2-3 years because of issues at time of underwriting, but no adviser could survive on the ridiculous and insulting figures suggested by Trowbridge.
I don't believe that John above is correct in stating that the AFA should get a vote of 'No Confidence'. This organisation hasn't supported the Trowbridge Report per se. But it's facing some heavy pressure from interest groups and in endeavouring to represent life-risk advisers the AFA wants to advocate what's in their interest while balancing that with what's good for the insurance-buying public.
What the Report recommends is unsustainable, except for long-time advisers with large client bases. It will only exacerbate the under-insurance in Australia because most new advisers won't be financially viable. Unless there are opportunities arising from this which are not yet clear to us.
All very good ideas, but really, why are we all so concerned over one guy's view. I doubt very much if Mr Troubridge has ever walked into a financial planner's office or a risk adviser's office. It seems that we are all scared about what this report says, but it may not even get any further than just his opinion. Let's wait to see what happens, and tell our decision makers, what we do, how we have helped many that would otherwise have struggled, give them testimonials that show what a great adviser you are.