Managed accounts and FASEABY SIMON CARRODUS | THURSDAY, 30 JUL 2020 5:13PM I've always enjoyed irony, so the irony wasn't lost on me when I first read Standard 3 of the FASEA Code of Ethics (Standard 3). It's ironic because Standard 3 purported ... Upgrade your subscription to access this article
Join the growing community of financial advisers
with unlimited access to our latest news, research and analysis of the industry.
Become a premium subscriber today. |


Latest News
NCAs unlikely to solve retirement advice gap: HUB24, CFS
HUB24 and Colonial First State (CFS) say the New Class of Advisers (NCA) will unlikely solve the retirement advice gap Australians face, noting the focus needs to be on helping reduce friction for those with complex advice needs.
Advised cover faces claims data test
Group superannuation insurance appears to outperform individual advised cover on some claim's measures, raising questions about the value of advice when it comes to protecting clients against disability.
ASIC stalls Sequoia bid to ditch cross guarantee deed
ASIC is again putting up roadblocks to Sequoia Financial Group's attempt to revoke the deed of cross guarantee with InterPrac Financial Planning, asking more questions and requesting more information before the group rids itself of all liabilities arising from the Shield and First Guardian disaster.
Praemium's new leadership toughens earnings yardstick
Praemium's new leadership will be keeping a close eye on costs, with new chief executive Denis Orrock noting he will make sure the technology upgrade underway translates into stronger earnings and better returns for shareholders.

Further Reading
Cover Story
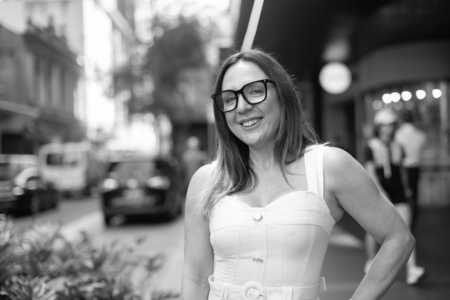
Advice with soul
SACHA BURCHGART
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
Though she initially tried, Sacha Burchgart couldn't escape the call of a career in financial advice; it just took staring down her own mortality to see what's possible when you do things differently. Jamie Williamson writes.
Expert Feed
How technology is turning tax complexity into client clarity
What used to be a relatively simple back-of-the-envelope calculation is now much more challenging, Morningstar says.
Why Australia's financial advisers will be more valuable in 10 years, not less
Despite a rise of innovative solutions across the wealth management sector, financial advisers will prove valuable for in-person advice.
What America's $1 trillion direct indexing boom tells us about the evolution of MAs
What Australia can learn from direct indexing, a tax-efficient form of managed accounts utilised in the US.

Stonepoint is another lesson in fund governance and investor protection
The demise of the Stonepoint Capital Fund may have gone under the radar for many, but proves an important point for independent governance when examined.




After 38 years in advice I believe most advisers shouldn't offer investment advice, nor charging fees for doing so. Competency is thin on the ground or non-existent. Most can explain the rules around tax, superannuation (a subset of tax) and how to deal with the various life and financial changes in generic terms - valuable in itself and can be almost guaranteed to be sound, if an adviser is competent and well-informed. Their role then becomes one of guidance and mentoring to ensure correct and timely steps are taken so clients achieve optimal pathways. As to investing - advisers know little (often less) than their clients. Everyone is guessing, but no one is saying so.
Conflicts of interest occur when one pretends to know more than one does - especially when investment advice is required to attract fees. We break our fees down, and offer investment advice as only a small portion of our service and allow clients to do their own transactions - follow their own path, with guidance from us on a 'best efforts' basis.
We tell them no one knows what tomorrow will bring, so we show them how best to avoid risks and let them follow their own, now better informed instincts We have the lowest PI premium in the country and have never had a complaint to deal with in our 38 years - other than by one fund manager/banker who didn't like us telling the truth about them...and they withdrew after a small " we said XYZ were bastards and we're sorry we did, but they are" apology.
Are other advisers out there also less concentrated on investment advice and more on mentoring and explainations of markets and risks, as we are? After being fee-for-service for 30 years we don't just manage but actually eliminate every potential conflict of interest, including that one of 'knowing best'. eg, we use Netwealth products because they allow/encourage clients to do transactions (as do we) and we charge less for clients who do so, as it reduces our risks of advice.