The care factorBY TONY STEPHENS | THURSDAY, 25 JUL 2019 4:04PM A good friend of mine lost his son to cancer not long ago, something no parent should ever have to experience. Even though this would have been one of the hardest things he will ... Upgrade your subscription to access this article
Join the growing community of financial advisers
with unlimited access to our latest news, research and analysis of the industry.
Become a premium subscriber today. |


Latest News
HNW clients value quality over fees: Praemium
High-net-worth (HNW) Australians who receive ongoing financial advice are more confident in their investments than those managing their wealth alone, new research from Praemium and CoreData found.
TAL launches new campaign focused on mental health
TAL has launched a new campaign, working with youth media group The Daily Aus, and partners with the AFLW, aimed at promoting mental wellbeing.
Selfwealth expands into full-fledged wealth platform
Trading platform Selfwealth has launched three managed portfolios, expanding from online brokerage into a wealth platform.
Adviser increase the 'strongest' since FY20: Padua WealthData
The number of financial advisers has risen to 15,169, with net gains of six new members this week, according to Padua WealthData's analysis.

Further Reading
Cover Story
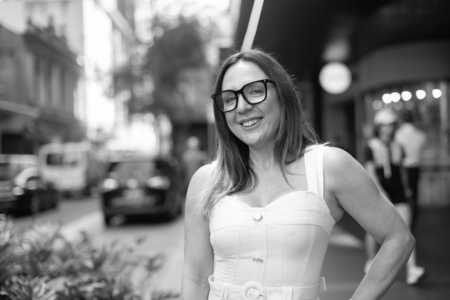
Advice with soul
SACHA BURCHGART
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
Though she initially tried, Sacha Burchgart couldn't escape the call of a career in financial advice; it just took staring down her own mortality to see what's possible when you do things differently. Jamie Williamson writes.
Expert Feed
What America's $1 trillion direct indexing boom tells us about the evolution of MAs
What Australia can learn from direct indexing, a tax-efficient form of managed accounts utilised in the US.
SMSF changes unlikely to deter those seeking greater control over superannuation
HLB Mann Judd's Mitchell Markwick believes the recent changes will not slow down the rapid growth in SMSFs.

Stonepoint is another lesson in fund governance and investor protection
The demise of the Stonepoint Capital Fund may have gone under the radar for many, but proves an important point for independent governance when examined.
A never ending story of levies
The extensive processing period for Shield and First Guardian complaints means financial advisers will likely not be able to see an end to a series of ...


I am a 30 year risk specialist. With respect, this article is repeating the old shibboleth that because a risk policy is " old" it is , ipso facto, not "adequate " It ain't necessarily so. Take IP - in 1988 it was indeed bad - non-coterminous benefit periods, injury definitions designed never to pay for a crook "tradie's back", exclusions for injury involving a "material breach of law" and "plague limitations" on No 4 Statutory Funds. It started to improve in the 90's, and by the mid 2000s, was much improved under the influence of small innovative insurers, all since subsumed into larger insurers. Then insurers discovered they had not priced for claims under the improvements, so little delightful "improvements" such as Capability Clauses and Criminality Clauses were introduced.
Watch out, we are heading backwards, and once all the risk specialists depart under the glare of FASEA & LIF, the insurers will have a picnic with part -time risk advisers.
Trauma & Own Occupation TPD have improved, but if you want some fun, compare stroke definitions today. Severity still abounds in some stroke definition cases
Finally the best value an adviser can provide is at claim. Yet I am still alarmed at the number of holistic advisers who refer the potential claimant direct to the insurer and do not get involved. That is bad business practice, BUT it might also now be a breach of FASEA rules
I do agree a competent adviser review should pick issues with low ( or high ) sum insureds, incorrect beneficiaries etc but please read, and understand, the risk policy terms and conditions
Caring for my clients is and has always been my number one priority (as my business ethos prior to joining this industry and while I'm still a part of it is "look after your clients and the rest takes care of itself"). Sadly, my ability to now do that like I used to has been systematically eroded the last 3-4 years by ASIC's hidden agendas, LIF's constraints and diminishing adviser remuneration, over the top Best Interest Duty compliance obligations and the deceitful, conflicted ambitions of FASEA.
So with all due respect Tony, I'd love to care more for my clients but the regime advisers are currently dealing with makes it near impossible to do that now. And it just infuriates me.