Changing face of insuranceBY OLIVIA SARAH-LE LACHEUR | FRIDAY, 2 FEB 2018 2:38PM The pace of change in Australia's income protection (IP) offering has gathered significant steam in recent years. For advisers who have been in the industry for a while now, you ... Upgrade your subscription to access this article
Join the growing community of financial advisers
with unlimited access to our latest news, research and analysis of the industry.
Become a premium subscriber today. |


Latest News
HNW clients value quality over fees: Praemium
High-net-worth (HNW) Australians who receive ongoing financial advice are more confident in their investments than those managing their wealth alone, new research from Praemium and CoreData found.
TAL launches new campaign focused on mental health
TAL has launched a new campaign, working with youth media group The Daily Aus, and partners with the AFLW, aimed at promoting mental wellbeing.
Selfwealth expands into full-fledged wealth platform
Trading platform Selfwealth has launched three managed portfolios, expanding from online brokerage into a wealth platform.
Adviser increase the 'strongest' since FY20: Padua WealthData
The number of financial advisers has risen to 15,169, with net gains of six new members this week, according to Padua WealthData's analysis.

Further Reading
Cover Story
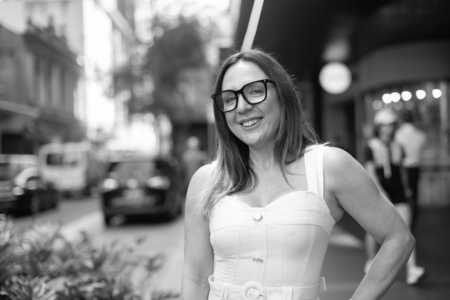
Advice with soul
SACHA BURCHGART
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
FOUNDER & MANAGING DIRECTOR
BURCHEART PTY LTD
Though she initially tried, Sacha Burchgart couldn't escape the call of a career in financial advice; it just took staring down her own mortality to see what's possible when you do things differently. Jamie Williamson writes.
Expert Feed
What America's $1 trillion direct indexing boom tells us about the evolution of MAs
What Australia can learn from direct indexing, a tax-efficient form of managed accounts utilised in the US.
SMSF changes unlikely to deter those seeking greater control over superannuation
HLB Mann Judd's Mitchell Markwick believes the recent changes will not slow down the rapid growth in SMSFs.

Stonepoint is another lesson in fund governance and investor protection
The demise of the Stonepoint Capital Fund may have gone under the radar for many, but proves an important point for independent governance when examined.
A never ending story of levies
The extensive processing period for Shield and First Guardian complaints means financial advisers will likely not be able to see an end to a series of ...


I think there is a con in place. Insurers are very reluctant to separate income protection losses in retail from those in group super.
Insurers please separate the actual losses. Insurers should get out of non-underwritten group income protection before they scream IP losses. Otherwise retail clients and their advisers will lose whatever trust is left.
I agree with the previous comment. There is a very real difference between what I would term a "proper contract" (full fact find, S.O.A, full advice, properly underwritten and adviser support at claim). Rather than "the do you want IP? - sign here contracts", and oh and by the way we will underwrite at claim time. Often sold or marketed by the same insurer.
Yes, the above comments are worthwhile. We do know however that we in Australia have among the very best income protection policies available. Those in the UK and the US offer nowhere near as many ancillary benefits as we do. For instance, often waiting period are not less than 3 months and benefit payments periods to age 65 aren't as readily available as they are here. If our clients want those they'll realise these come at a price.